A Blue Bond is a debt instrument that national governments, development banks and corporations issue to raise finance for marine and ocean-based projects that have long-term sustainability objectives and benefits. Blue Bonds work like conventional bonds wherein an investor lends capital to the bond issuer who pays back the initial investment plus an interest rate every year until the end of the bond’s term.
Definition and Key Features
Best for public or private issuer: Both
Ideal size of issuer: Large
A blue bond is a use-of-proceeds debt instrument issued by national governments, development banks, municipalities, and corporates to raise finance for water-related and ocean-based projects that have long-term sustainability objectives and benefits.
Blue bonds work like conventional bonds (i.e., the investor lends capital and the issuer repays the principal plus an annual coupon until the end of the bond's term) with one distinguishing feature: proceeds are ring-fenced for eligible blue projects. Repayment continues to rest on the issuer's general creditworthiness rather than on the performance of the projects.
Like conventional bonds, blue bonds can broadly be categorised by the type of issuer, distinguishing between private bonds (corporate and project-specific) and public bonds (sovereign and municipal).
Private blue bonds are primarily used to support the acquisition, expansion, or restructuring of blue-oriented initiatives (e.g., sustainable fisheries). They can be listed on stock exchanges or issued through private placement. Long-term investors such as pension funds and insurance companies are often attracted to this type of instrument due to features such as long tenors and fixed-rate returns. Such features make blue bonds particularly suitable for large-scale infrastructure projects such as maritime transportation or marine renewable energy.
Types of issuers and investors
Issuers: sovereigns, municipalities, financial institutions, multilateral development banks, and corporates
Investors: private actors (e.g., pension funds, insurance companies, high-net-worth individuals, family offices, asset managers, investment banks) and non-private financial actors (e.g., development banks, sovereign wealth funds, and foundations)
Process of issuance
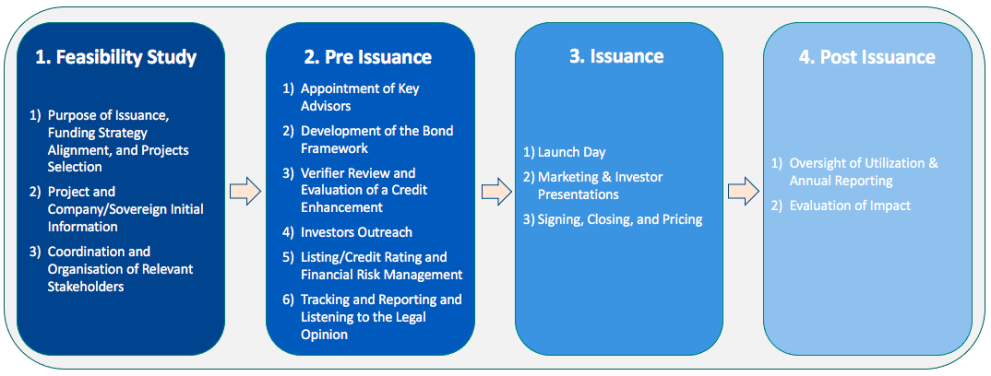
Issuance typically unfolds in four stages. It starts with a feasibility study to scope funding needs and stakeholders. Pre-issuance involves building the bond framework, lining up advisors, obtaining the credit rating, and conducting investor outreach. Issuance covers marketing, pricing, and closing the deal. Finally, post-issuance tracks how proceeds are used and reports on impact.
Criteria and legislation
Standards and labelling
There is no single global standard for blue bonds. Instead, participants have converged around the ICMA (International Capital Market Association) Green Bond Principles (GBP), which now serve as de facto market practice for issuance. The GBP govern how a bond is structured, managed, and reported (e.g., use of proceeds, project evaluation and selection, management of proceeds, and reporting) but they do not define what counts as “blue”.
For several years, issuers filled that gap with bespoke frameworks. The Republic of Seychelles' 2018 issuance, the world's first sovereign blue bond, is the clearest example: with no blue standard yet in existence, the World Bank structured a custom instrument tailored to the Seychelles' circumstances.
Two documents have since consolidated market practice, both operating as overlays on the green bond architecture rather than as standalone taxonomies. The International Finance Corporation (IFC) first published in 2022 and then updated in 2025 its Guidelines for Blue Finance, which set out blue project eligibility and now cover an expanded range of sectors – including water security, plastics, shipping, aquaculture and marine conservation – together with guidance on performance-linked structures. In September 2023, ICMA, the IFC, the UN Global Compact, the UN Environment Programme Finance Initiative and the Asian Development Bank jointly published Bonds to Finance the Sustainable Blue Economy: A Practitioner's Guide, offering indicative eligible categories, impact evaluation guidance, and reporting expectations. The two documents differ in scope: the IFC Guidelines cover both freshwater and ocean-related activity, while the Practitioner's Guide only addresses ocean-related projects.
In practice, issuers can structure blue bonds under the GBP and point to one or both guidance documents to substantiate the blue purpose. A 2026 issuance by Jordan’s Housing Bank illustrates the pattern: the bond was issued under the bank's existing Green Bond Framework and aligned to both the ICMA GBP and the IFC's Guidelines, attracting a USD 100 million investment from the European Bank for Reconstruction and Development (EBRD) as the first tranche of a USD 200 million programme. It is the first blue bond in Jordan and in the wider Southern and Eastern Mediterranean region, with proceeds directed towards sustainable water and wastewater management, principally the National Water Carrier Project.
What qualifies as a blue project
To qualify as blue, a project must satisfy two conditions: i) it must fall within the eligible green categories stablished under the GBP, and ii) it must contribute to Sustainable Development Goal (SDG) 6 (Clean Water and Sanitation) or SDG 14 (Life Below Water), with outputs and outcomes directly related to one or more of their target indicators.
The GBP supply the instrument architecture, while the SDGs supply the definition. An issuer applies both: the GBP to structure and report on the bond, and the SDG-based eligibility test to determine which projects the proceeds may fund. SDG alignment is therefore assessed at the project level and inherited by the bond through its framework, rather than being applied as a separate bond-level test.
The EU framework
In the European context, the EU has no separate label for blue bonds. Issuers seeking an EU label use the European Green Bond designation set out in the European Green Bonds Regulation (EU) 2023/2631, which requires proceeds to be allocated to activities aligned with the EU Taxonomy Regulation (EU) 2020/852 and its delegated acts, subject to a flexibility pocket of up to 15% for activities where technical screening criteria are not yet in force. One of the Taxonomy's six environmental objectives – the sustainable use and protection of water and marine resources – points directly to the sustainable blue economy and the Mission's goals. Among the remaining Taxonomy objectives (i.e., climate change mitigation, climate change adaptation, the transition to a circular economy, pollution prevention and control, and the protection and restoration of biodiversity and ecosystems), several are also closely aligned with the Mission's goals.
Key considerations: strengths and challenges
Use for Mission Ocean's Objectives: Blue bonds can be used to finance projects and activities related to Mission Ocean's three objectives: the protection and restoration of marine and freshwater ecosystems, the elimination of marine pollution, and the development of a carbon neutral and circular blue economy.
Investment Promotion: Blue bonds serve as an innovative bridge to attract private investments, especially from capital markets, into marine health-related projects. For example, Small Island Developing States, whose economies depend heavily on the long-term health of their surrounding oceans, could benefit significantly from the opportunities presented by blue bonds to finance strategically designed portfolios of projects that bring in additional capital, support more effective project implementation, and deliver a meaningful impact on the overall region's blue economy.
Broad Sustainability Improvement: Blue bonds are designed to raise capital for projects that have a direct impact on ocean and marine-related issues while also advancing other sustainability priorities, such as social inclusion, economic growth, and environmental protection. A blue bond's impact therefore goes beyond marine conservation and restoration, affecting several other dimensions of the economic and environmental context in which the proceeds are deployed.
However, blue bonds also face some challenges. These include:
Price: Thematic bonds such as blue bonds are not necessarily cheaper than conventional bonds, and pricing is not determined by one use of proceeds as compared to another use. The key factor is the credit rating of the instrument, which investors prioritise in determining the yield they require. This rating will vary based on factors such as the issuer, credibility, and the market in which the blue project will be located.
Fungibility and Impact Demonstration: As with other thematic instruments, it is essential that the capital raised from a blue bond is only deployed towards blue-focused activities as stated in the issuance documentation. To ensure credibility and transparency, a comprehensive measurement, reporting, and verification (MRV) system needs to be put in place by the issuer. However, this can be complex, time consuming, and resource intensive. Even with an effective MRV system in place, demonstrating the impact of the bond proceeds can be difficult.
Earmarking: Linking bonds to specific expenditures reduces the issuer’s flexibility in allocating the raised capital, which can lead to the overfunding or underfunding of individual initiatives.
Case Studies
Case study: World Bank Blue Bond Against Plastic Pollution in the Oceans
Mission Ocean Objectives reached: 1 & 2
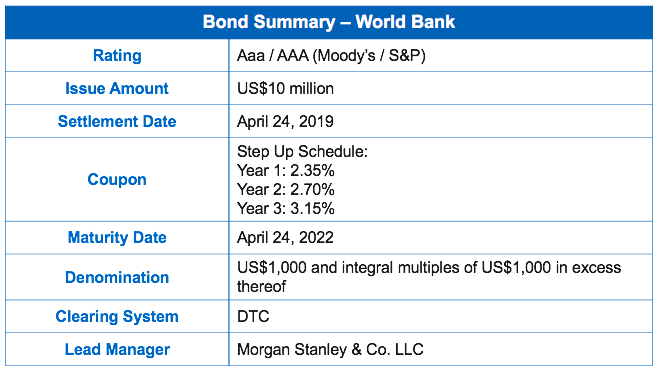
In 2019, the World Bank launched a Blue Development Bond to engage investors on marine plastic pollution, channelling the bond’s proceeds towards development projects aimed at sustainable water management and ocean pollution reduction. The bond represents one in a series of ongoing efforts by the Bank to engage with investors on initiatives to conserve freshwater and marine resources.
Structured as a callable, step-up fixed-rate bond, it was targeted at both individual and institutional investors, pricing successfully on 2 April 2019 and raising US$10 million. The exclusive distributor for this bond was Morgan Stanley & Co LLC. The bond adheres to the GBP and focuses on supporting SDG 14 and SDG 6. Projects targeted for support range from large regional fisheries programmes to water and marine pollution reduction from improving water sanitation to the support of sustainable coastal development.
World Bank Blue Bond – Summary
Source: World Bank, 2019